Money
The annual fee is the first number anyone looks at on a credit card and close to the least useful one. It is a cost. It is not a verdict on whether the card is worth carrying.
I carry nine cards, seven personal and two corporate, and the whole stack is published on the credit cards page with what each one is actually for. Four of the nine have no annual fee. The most expensive one is $799.
Do The Subtraction Before The Judgement
A $799 card with $400 of credits you would have spent anyway costs $399. A no fee card you never use costs nothing and earns nothing. Compare after credits, not before.
The Platinum Card is $799 a year. It carries a $200 annual travel credit and a $200 annual dining credit. If those are things you were going to spend money on regardless, $400 comes off the fee on day one and the real cost is $399. What that $399 buys is lounge access and hotel status.
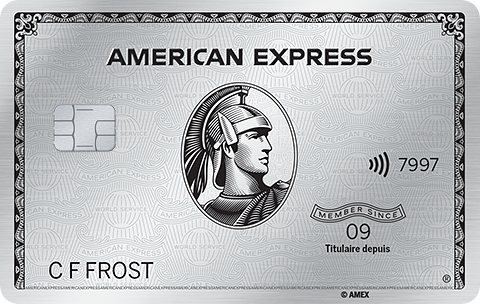
That is a defensible number or it is not, depending on how much you travel. The point is that $399 is the number you have to judge, and almost nobody gets to it because they stopped at $799 and moved on.
The same arithmetic runs the other way. A no fee card that sits in a drawer has a real cost of zero and a real return of zero. Zero is not a win. It is just a small number.
Credits Only Count If You Would Have Spent Them
This is where the maths goes wrong for most people. A credit you would not otherwise have used is not a discount on the fee. It is the card persuading you to spend $200 to save $200, which is spending $200.
So the test is narrow. Would this money have left the account anyway, in this category, this year? If yes, subtract it. If no, it is not a credit, it is a coupon, and coupons do not belong in the fee calculation.
The Rate Only Matters If You Carry
There is a second number people confuse with the fee, and that is the interest rate. On a rewards card it should be irrelevant, because the balance should never sit.
Twenty one ninety nine against four percent back is not a trade, it is a loss. If something has to sit, it sits on the twelve ninety nine card.
That is what a low rate card is for. It is not a rewards card that happens to be cheap, it is a separate tool with one job, and putting a balance on the wrong card wipes out a year of category earning in a couple of months.
What This Looks Like Across A Stack
Nine cards sounds like a lot until you look at what each one does. Some are held for a category rate. Some are held because they have no foreign transaction fee. Some are held because they earn into a currency the others also feed, and one balance you can actually spend is worth more than three you cannot.
The stack costs a bit over $1,111 a year to keep open. That is the honest number and it is on the money hub. Whether it is worth paying is a subtraction, done card by card, after credits.
None of this is advice, and the right stack for someone else is a different stack. The method is the transferable part.
Common Questions
How do you decide whether an annual fee is worth paying?
Subtract the credits you would have spent anyway, then judge what is left. A $799 card with $400 of credits you would have used regardless costs $399, and $399 is the number to argue about.
Does that mean no fee cards are always worse?
No. It means a no fee card you never use costs nothing and earns nothing, which is not a win, just a small number. Four of the nine cards I carry have no annual fee and each is held for a specific job.
What if I would not have spent the credit?
Then it is not a credit, it is a coupon, and it does not belong in the fee calculation. Spending $200 to save $200 is spending $200.
Does the interest rate matter on a rewards card?
Only if you carry a balance, and on a rewards card you should not. Twenty one ninety nine against four percent back is a loss, not a trade. If something has to sit, it sits on a dedicated low rate card.
What does the whole stack cost to keep open?
A bit over $1,111 a year across nine cards, seven personal and two corporate. That figure is published on the money hub alongside the cards themselves.